Japan ATM Withdrawal Guide: Fees, Limits, Cash Tips and Best Cards
Start with Seven Bank or Japan Post when you need yen, review the ATM fee and choose JPY when offered conversion. This guide explains foreign-card acceptance, withdrawal limits, phone payments and a practical backup-card setup.
Quick answer: try Seven Bank at 7-Eleven, select English, review the withdrawal fee and choose JPY if offered currency conversion. Bring a physical card and keep some yen for cash-only stops. Jump to the seven withdrawal steps or compare ATM networks.
How to withdraw cash in Japan without getting stung
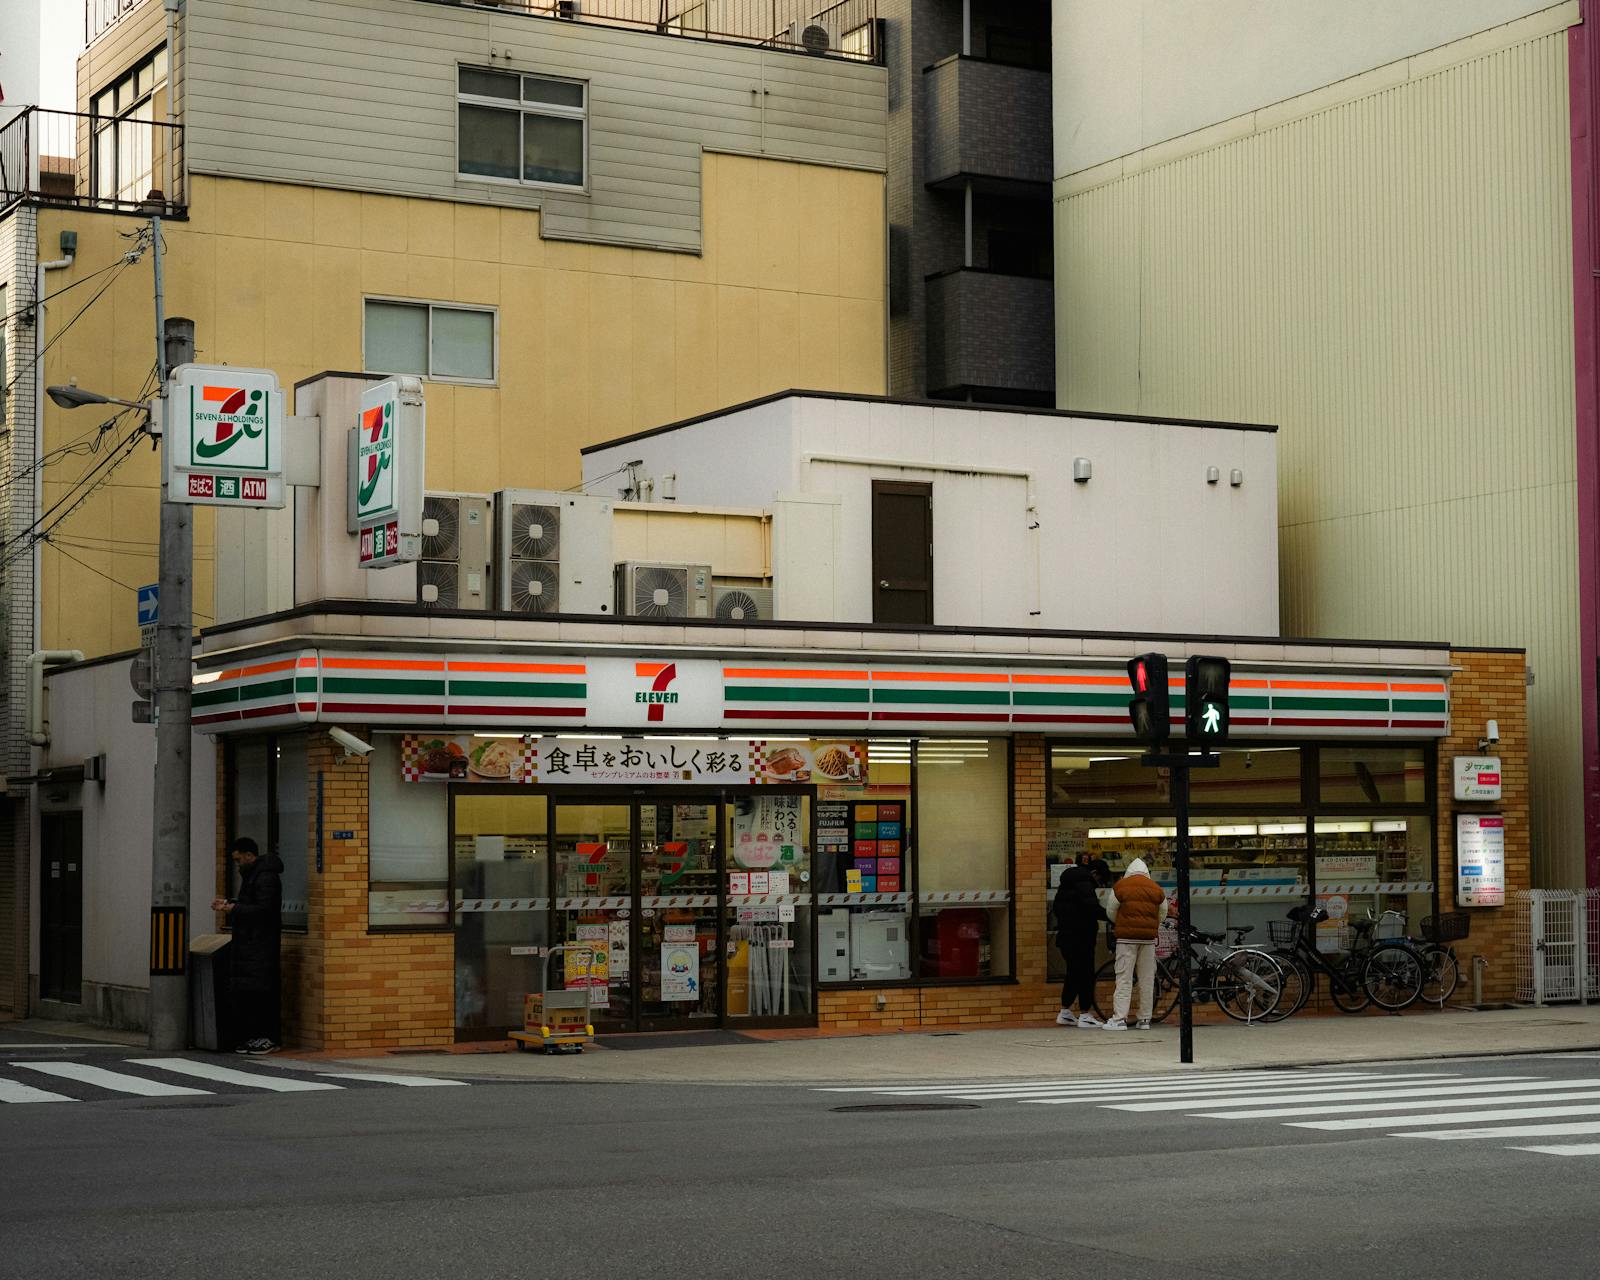
- Find a foreign-card ATM. Start with Seven Bank at 7-Eleven, Japan Post, or AEON.
- Select English. Do this before inserting your card if the screen gives you the option.
- Choose withdrawal. Select savings or current/checking if the ATM asks for account type.
- Enter the amount in yen. Remember that smaller shops may not love huge notes, so break a 10,000 yen note at a convenience store if needed.
- Review the ATM fee. If it looks unreasonable, cancel and try another network.
- Choose JPY if offered a currency choice. Never let the ATM convert into your home currency.
- Take your card, receipt and cash. Japanese ATMs can retract items if you leave them too long.
Japan is not “cash only” anymore. You can tap cards in convenience stores, use IC cards like Suica or ICOCA on trains, and pay by card in many hotels, chains and department stores. But cash still solves problems every day, especially at smaller restaurants, temples, shrines, local buses, rural stops, guesthouses and old-school ticket counters.
The good news is that getting yen from an ATM is straightforward once you know where to go. The expensive mistakes are simple too: using a card with foreign transaction fees, choosing home-currency conversion at the ATM, withdrawing tiny amounts too often, or assuming any random Japanese bank ATM will accept your overseas card.
Do you still need cash in Japan?

Yes. For a first trip, the safest assumption is that you’ll use card and digital payments often, but cash will still save the day in enough places that you shouldn’t travel without it.
Cards are usually fine at hotels, larger shops, convenience stores, many train stations, major attractions, chain restaurants and department stores. Cash becomes more important at smaller ramen shops, local izakayas, temples, shrines, older restaurants, rural accommodation, markets, local buses, coin lockers and smaller towns.
For Tokyo, Kyoto, Osaka and Hiroshima, I’d still carry at least 10,000–20,000 yen. If you’re going into the countryside, staying in a ryokan, hiking the Nakasendo or Kumano Kodo, visiting smaller islands, or moving through towns where convenience stores are less frequent, withdraw more before leaving the city.
Can you just tap your phone and skip cash?
This is the question more travellers ask every year, and the honest answer for 2026 is: mostly yes in the big cities, but not entirely. If you stay in central Tokyo, Kyoto and Osaka, eat at chains and shop in larger stores, you can get a long way on card and phone alone. Outside that bubble, the cash-only long tail is still real.
iPhone: Suica, PASMO or ICOCA can be added to Apple Wallet on an iPhone 8 or later or Apple Watch Series 3 or later, with current software; see Apple’s compatibility and setup instructions. Top-up acceptance depends on the payment card. Android: mobile PASMO requires an Osaifu-Keitai-compatible device; do not assume an overseas phone with NFC supports it. See Google’s PASMO requirements. A physical IC card is a practical fallback. IC-card acceptance does not replace a cash buffer.
Where tap-to-pay still fails you: small family restaurants, ramen counters with a ticket machine, temples and shrines, local markets, older guesthouses, some rural buses, and cash-only entry fees. So treat your phone as the default for everyday spending, but keep a cash buffer for the places that quietly refuse cards. The setup in this guide is designed for exactly that — spend on card or phone where you can, and have yen ready where you cannot.
Best ATMs in Japan for foreign cards
The most important thing to know is that many domestic Japanese bank ATMs are not designed for overseas cards. You want machines that clearly support international cards and show the relevant Visa, Mastercard, PLUS, Cirrus, JCB or Discover logos.
1. Seven Bank ATMs at 7-Eleven
Seven Bank is the easiest default for most travellers. The network is huge, 7-Eleven stores are everywhere on the main tourist route, menus are available in English, and Seven Bank officially lists overseas cards as usable at its ATMs. Seven Bank also states that the withdrawal limit for overseas cards is 100,000 yen per withdrawal, with a lower 30,000 yen limit for magnetic-stripe transactions.
7-Elevens are easy to find, and Seven Bank has an English ATM locator if you ever get stuck. Fees for cards issued overseas vary by card brand, so don’t assume every withdrawal is free. Check the fee shown on the ATM screen before confirming, then focus on avoiding extra fees from your own bank or card issuer — which is exactly what a low-fee travel card is for.
2. Japan Post Bank ATMs
Japan Post Bank is the best backup to know, especially outside the biggest city centres. Japan Post says cards issued overseas with marks including Visa, PLUS, Mastercard, Maestro, Cirrus, JCB, China UnionPay and Discover can withdraw cash at Japan Post Bank ATMs.
The key limits are different from Seven Bank. Japan Post lists a 50,000 yen single-transaction withdrawal limit, and says a 220 yen ATM usage fee may apply for some cards issued abroad. Hours vary by ATM type and location, so Japan Post is useful, but not always as frictionless as 7-Eleven.
3. AEON Bank ATMs
AEON Bank is a useful extra option at malls, airports, Ministop stores, some convenience-store locations and major train stations. AEON says more than 6,500 ATMs nationwide can be used to withdraw Japanese yen with cards issued by overseas banks or credit-card companies.
I’d treat AEON as a good backup rather than the first ATM you hunt for. It’s handy when you’re already in an AEON mall or near one of its supported locations, but Seven Bank is usually simpler to find on normal travel days.
4. Lawson and other convenience-store ATMs
Lawson Bank and other convenience-store ATMs can also work with foreign cards, but the experience can vary more by card, machine and location. They’re worth trying if Seven Bank isn’t nearby, but I wouldn’t build my arrival-day cash plan around them.
5. Airport ATMs
Narita, Haneda and Kansai all have international-card ATM options. Withdrawing a small amount on arrival is sensible if you’re heading straight to a train, bus, local guesthouse or food stop. You don’t need to exchange a huge amount at airport money changers if your card setup is good.
| ATM network | Best use | Withdrawal limit | Operator fee | Traveller note |
|---|---|---|---|---|
| Seven Bank | Default first choice | 100,000 yen per withdrawal (30,000 yen for magnetic-stripe) | Fees vary by card brand. Check the charge on screen before confirming. | Widely available at 7-Eleven; service hours can vary by card and location. |
| Japan Post Bank | Rural and small-town backup | 50,000 yen per transaction | 220 yen may apply for some overseas cards | Good coverage, but hours vary by ATM and location. |
| AEON Bank | Malls, airports, Ministop, stations | 50,000 yen per transaction (6,500+ ATMs nationwide) | Fees vary by issuer; AEON specifically lists 75 yen for UnionPay withdrawals. | Useful backup when nearby; check your card’s charge on screen. |
| Lawson Bank | Convenience-store backup | 50,000 yen per transaction | Check the displayed fee; do not assume one flat fee for all overseas cards. | Worth trying, but Seven Bank is easier to rely on. |
Japan ATM fees: what you’re actually paying
There are usually three possible costs when you withdraw cash in Japan:
- The Japanese ATM operator fee. This is the charge shown by the machine, if one applies. Japan Post says 220 yen may apply to some overseas cards. Seven Bank and AEON fees depend on the card; check the screen rather than assuming a network is free.
- Your card issuer’s ATM or overseas withdrawal fee. This comes from your bank, not Japan.
- The exchange-rate cost. This is where bad cards quietly hurt you through foreign transaction fees, poor rates or dynamic currency conversion.
Compare the total cost of the withdrawal. A small operator fee can be worth paying for a convenient machine, but your card may add a separate withdrawal or conversion charge. A low-fee card can reduce those costs without guaranteeing that every withdrawal is free.
The rule that saves the most money: if the ATM asks whether to charge you in yen or your home currency, choose Japanese yen. Let your own card do the conversion. Home-currency conversion at the ATM is usually where the bad exchange rate sneaks in. (Note that JCB, Discover, UnionPay, American Express and Diners Club cards aren’t offered this currency choice at Seven Bank anyway, so this mainly matters for Visa and Mastercard.)
An ATM withdrawal can involve the local operator’s charge, your card provider’s withdrawal fee and currency conversion. Check all three before confirming. Wise’s allowance depends on where your card was issued; Ubank does not charge its own overseas ATM fee, but the operator may. See each provider’s fee schedule rather than treating a fee-free card as a guarantee of a free withdrawal.
Best card setup for Japan
Our recommendation is Ubank for eligible Australians spending from AUD, and Wise for international readers where its card is available. Ubank has no fee of its own for overseas purchases or ATM withdrawals and uses Visa’s conversion rate. Wise lets eligible readers hold yen and make international transfers, with conversion fees shown before exchange. Check Wise card availability and fees for your home country; Ubank is an Australian account.
Order physical cards well before departure and check each provider’s delivery estimate. A digital wallet does not replace a physical card at every ATM.
Wise’s withdrawal allowance depends on where your card was issued. For Australian-issued cards, the allowance is AUD400 per account per month, followed by a 2.69% fee on the amount above AUD400. That Australian structure began on 1 May 2026 and has no withdrawal-count cap. Currency conversion and local ATM charges can still apply. Check your own country’s pricing in the app before flying.
If you already have a suitable Ubank or Up account, compare its travel costs before adding another card. Carry a physical backup from a separate provider, ideally on a different network, plus some yen. Check the logos on the cards you receive; two different providers can still issue the same network.
| Card | FX rate & fees | ATM allowance | Best for |
|---|---|---|---|
| Ubank (AU) | Visa conversion from AUD; no Ubank international card-payment fee. | No Ubank overseas ATM fee; operator fees and account limits apply. | Our recommended starting point for eligible Australians spending directly from AUD. |
| Wise | Mid-market rate with a small, transparent conversion fee. Hold and spend yen directly. | Allowance depends on issuing country. AU: AUD400 per month, then 2.69% on the amount above it; operator and conversion fees are separate. | Our recommended option for international readers where the card is available; also a possible Australian backup for currency balances and transfers. |
| Revolut | Exchange allowances, rates and out-of-hours charges depend on your country and plan. | Amount and withdrawal-count allowances, then percentage or minimum fees, depend on your country and plan. | A separate provider and multi-currency option; check your actual card network. |
| Up Bank (AU only) | No foreign transaction fee. Mastercard’s rate with no markup. | No Up fee on overseas ATM withdrawals and no monthly fee-free cap (the local ATM operator may still charge its own). | Australians who prefer Up’s budgeting features and Mastercard spending from AUD. |
Provider fees: Ubank fees and limits and Up overseas card information. ATM charges are separate from card-provider charges.
Want the full breakdown? See our dedicated Wise vs Revolut vs Up comparison for travel.
Simple Japan money setup
- Main spending card: Ubank is our pick for eligible Australians spending from AUD; Wise is our pick for international readers where available, subject to local fees and card limits.
- Backup card: use a separate provider, ideally on a different network. Wise can also be useful if you want to hold yen or make transfers.
- Cash buffer: withdraw enough yen for several days at a time, especially before rural travel.
Ubank travel fees and card limits
Ubank does not charge its own international purchase or overseas ATM-withdrawal fee. Purchases are converted from AUD using Visa’s rate. ATM operators may charge separately, and account withdrawal limits still apply. Check Ubank’s current fees and limits and your app before departure.
Check eligibility, card-order costs and delivery times before applying. Keep a physical card for ATMs.
Ubank $30 signup bonus: eligible new customers must join by 24 October 2026, enter AFWLLL7 on the About you screen and make five eligible card purchases that settle within their first 30 days. Both participants must be 18+; customers who closed all their Ubank Spend and Save accounts in the preceding 12 months are excluded. Allow up to 45 days for payment after the requirements are met. Full offer terms.
Set this up before you fly
A good Japan money setup is not just the card. You also want data working before you reach the ATM, because the first hour after landing is when you need maps, train routes, booking details and translation most.
Install your eSIM before departure
Saily’s Japan eSIM is the easiest add-on to pair with this ATM setup. Install it before you fly, then activate it when you land so you can find the nearest Seven Bank ATM, check train routes and pull up your accommodation details without hunting for airport Wi-Fi. It takes two minutes to set up and means you walk off the plane already connected.
How much cash should you withdraw?
For most city trips, I’d withdraw enough for several days rather than visiting an ATM constantly. A practical starting point is:
- Short city stay: 10,000–20,000 yen as a walking-around buffer.
- One week in Japan: 30,000–50,000 yen if you’ll use card and IC card often.
- Rural route or temple-heavy itinerary: withdraw more before leaving the city.
- Budget accommodation and budget travel: carry enough for laundry, local buses, small restaurants and cash-only sights.
Don’t overdo it. Japan is safe, but there’s no need to carry your whole trip budget in cash. The sweet spot is enough yen to avoid stress without turning your wallet into your entire savings account. Fewer withdrawals may reduce per-transaction fees, but larger withdrawals do not increase an amount-based monthly allowance.
For a first visit, use the 10-day Tokyo, Kyoto and Osaka itinerary to work out where you will need cash between city stops.
JR Pass, IC cards and cash

Cash is only one part of the Japan money system. For local transport, you’ll probably use Suica, PASMO or ICOCA. For intercity travel, you may be deciding whether a Japan Rail Pass is worth it.
The JR Pass is no longer an automatic yes. It works best for genuinely train-heavy routes. If you’re mostly staying around Tokyo, Kyoto and Osaka with only one or two big rail days, price individual rail fares first. If your route includes several long-distance Shinkansen trips in a short window, the pass can still make sense. For the full breakdown with real fares and worked examples, see our guide on whether the JR Pass is worth it.
Common Japan ATM mistakes
- Using a normal bank card with foreign transaction fees. This is usually more expensive than the Japanese ATM fee — a low-fee travel card removes it.
- Choosing your home currency at the ATM. Choose yen and let your card handle conversion.
- Withdrawing tiny amounts repeatedly. This can multiply operator fees or use up a withdrawal-count allowance. Amount-based monthly limits still apply whatever the withdrawal size.
- Assuming every ATM accepts foreign cards. Use international-card networks rather than random domestic ATMs.
- Leaving the card order too late. Physical travel cards take days to arrive — order before you fly.
- Landing without mobile data. Install your Japan eSIM before the flight.
- Relying only on one card. Carry a backup from a different bank or network.
Japan ATM FAQ
Can I use my Visa or Mastercard at any ATM in Japan?
No. Many domestic ATMs don’t support overseas cards. Start with Seven Bank, Japan Post Bank, AEON Bank or clearly marked international ATMs.
What is the Seven Bank withdrawal limit for foreign cards?
Seven Bank states that the overseas-card withdrawal limit is 100,000 yen per withdrawal. Magnetic-stripe card transactions are limited to 30,000 yen.
What is the Japan Post ATM withdrawal limit?
Japan Post Bank lists a single transaction withdrawal limit of 50,000 yen for overseas cards.
What’s the best travel card for Japan?
Our pick is Ubank for eligible Australians spending from AUD, and Wise for international readers where the card is available. Ubank charges no fee of its own for overseas purchases or ATM withdrawals; Wise has conversion fees and a country-specific withdrawal allowance. Local ATM fees can apply to either. Bring a physical backup card and some yen.
Can I travel Japan with just tap-to-pay and skip cash?
In the big cities you can get a long way on card, phone and a Suica or PASMO IC card added to your wallet. But cash-only spots are still common at small restaurants, temples, markets and rural stops, so carry a yen buffer as backup.
Should I exchange cash before arriving in Japan?
You usually don’t need to exchange much before arrival. Bring a little emergency cash if it makes you feel better, but a low-fee card plus a Seven Bank ATM on arrival is normally cleaner than using airport exchange counters.
Is Wise good for Japan?
Wise can be useful if you want to hold yen or make international transfers. It uses the mid-market exchange rate with a conversion fee. Check your issuing country’s withdrawal allowance and any card-order cost before deciding whether it fits your trip.
Is Revolut good for Japan?
Revolut can be another backup option. Exchange allowances, out-of-hours charges and ATM fees depend on your country and plan, so check the local terms. It may issue Visa or Mastercard; do not assume it uses a different network from your main card.
Is Up Bank good for Japan?
Up is an Australian budgeting account with Mastercard spending and no Up fee for overseas purchases or ATM withdrawals; local ATM fees and card limits still apply. We include it for comparison, while Ubank remains our main recommendation for eligible Australian travellers and Wise for international readers where available.
The bottom line
Japan ATM withdrawals are easy once you stop treating every machine and every card as equal. Use Seven Bank first, keep Japan Post and AEON in your backup list, choose yen at the ATM, carry enough cash for small businesses and rural days, and bring a card that doesn’t punish you with hidden currency costs.
Keep the setup simple: a suitable low-fee spending card, a physical backup from another provider, working phone data and a modest yen buffer. For eligible Australians, choose Ubank as the main spending card. For international readers, our recommendation is Wise where the card is available, after checking your home country’s fees. Order any new physical card early enough to test it before departure.
Disclosure: Some links in this guide are affiliate links — if you sign up through them, Backpacking Is Life may earn a small commission at no extra cost to you. ATM fees, card terms, withdrawal limits and bonuses can change, so confirm the final details with the ATM operator and your card provider before relying on them.
Japan trip setup links
The five-minute checklist that saves the most money and hassle — sorted before you fly:
- Australian readers: Join Ubank with code AFWLLL7 for the eligible $30 signup bonus. Offer conditions above apply.
- International readers: Explore Wise where its card is available in your home country. Check local fees and keep a second card plus cash.
- Add Revolut as a backup card
- Install Saily Japan eSIM before you fly
- Check JR Pass prices on Klook
- Read the full travel-card comparison guide
Card and ATM fees checked on 5 October 2026. Always review the machine’s charge and your provider’s current terms before withdrawing.
Useful official references
- Seven Bank: overseas cards usable at ATMs
- Japan Post Bank: International ATM Service
- AEON Bank: ATM information for overseas cards
- JNTO: currency and money information for Japan
- Wise: current Australian card pricing
- AEON: overseas-card withdrawal fees and limits
- Lawson Bank: overseas-card ATM questions
- Revolut: Australian Standard plan fees
Related Backpacking Is Life guides
Helpful next reads for planning the same trip, money setup, or travel tech.